Best Forex Brokers in the Philippines 2026
TL;DR: Exness is our top pick — GCash and local bank deposits in PHP, withdrawals in minutes, spreads from 0.3 pips. Runner-up: IC Markets for the tightest spreads in retail forex (Raw from 0.0 pips + $7 round-turn commission) — but card/e-wallet funding only, no GCash. Budget pick: FBS — $1 minimum and GCash funding, though your account sits under a Belize regulator.
Verdict first: which broker should a Filipino trader actually open?
Picking a broker from the Philippines has two layers: trading conditions (spreads, execution) and plumbing (can you get pesos in and out cheaply). Most lists only answer the first — yet a broker with world-class spreads is useless if funding it means an international wire and a conversion haircut every time you move money.
We scored six brokers on what actually differs for a Manila, Cebu, or Davao trader: GCash or Maya in the cashier, PHP deposit options, peso-friendly minimums, withdrawal speed, and which legal entity your account lands under. None holds a Philippine SEC license — there is no locally licensed retail forex broker — so the offshore entity in your client agreement is what matters.
Our pick is Exness: GCash and Maya deposits, direct transfers to BDO, BPI, Metrobank, UnionBank, and Landbank, minimums from PHP 500, withdrawals in minutes, spreads from 0.3 pips (0.0 on Raw/Zero — including gold most of the day).
IC Markets takes second for raw cost: Raw Spread averaged 0.02 pips on EUR/USD in independent 2026 testing with a $7 round-turn commission. The catch: no GCash, no Maya, no local bank rails, no PHP base, $200 minimum.
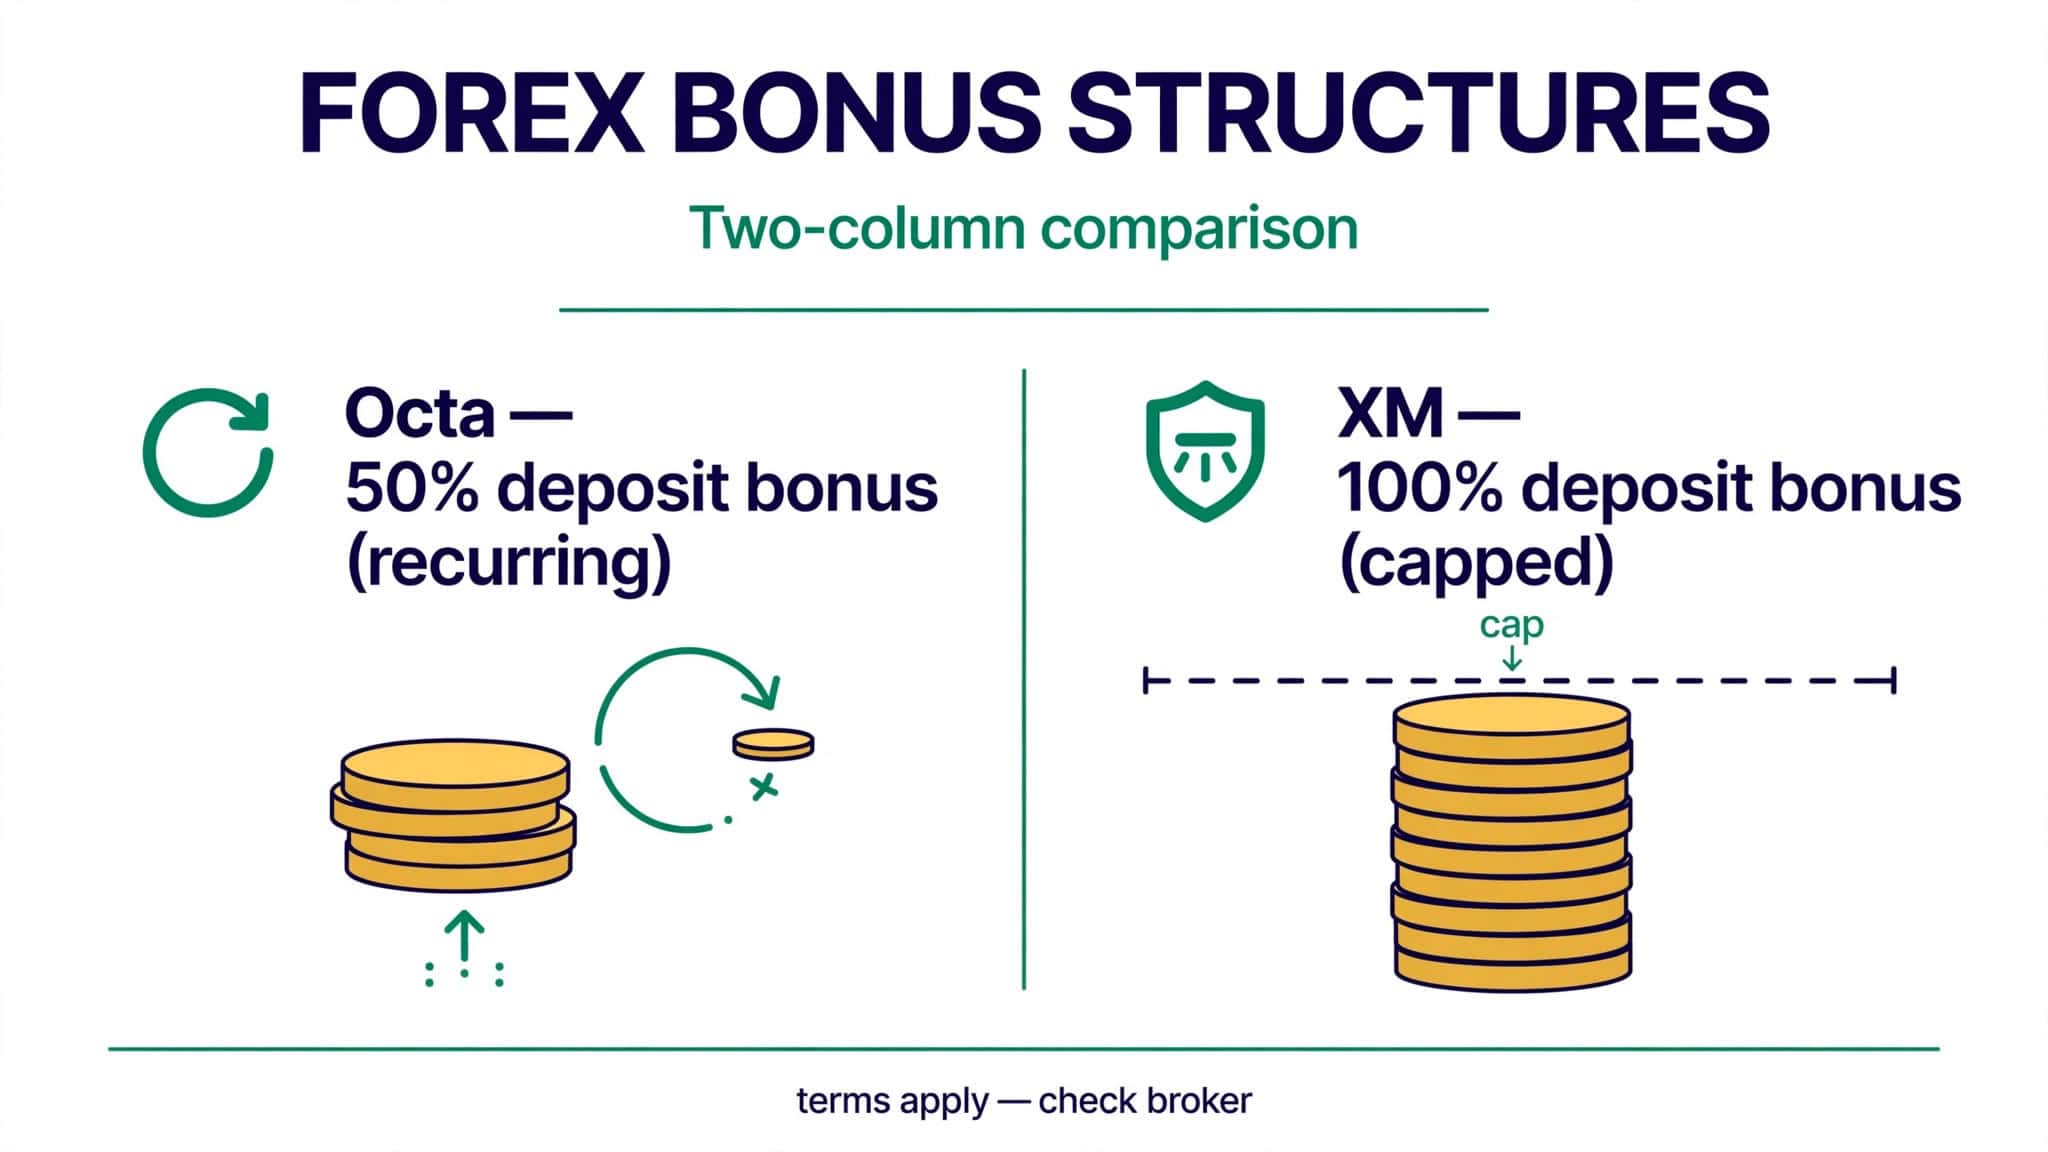
XM ($5 minimum, 100% deposit bonus), Pepperstone (deepest regulation, full TradingView — but USD-only funding), Octa (50% bonus on every deposit, 1:1000 leverage), and FBS ($1 minimum with GCash, but the weakest regulator) round out the list.
How we ranked these brokers
- Regulation check. Which licenses the group holds, and which entity a Philippine resident’s account actually opens under — an FCA license doesn’t protect you if your account is legally held by a Seychelles or Belize subsidiary.
- Cost testing. Typical EUR/USD spreads per account type, commissions, and conversion costs. Every number below was verified against broker-published figures or independent 2026 reviews; where we couldn’t verify, we say so.
- Funding-rail verification. Which brokers actually offer GCash, Maya, or Philippine local bank transfer in the cashier for PH residents — not just “Asia” in general.
- Account types and minimums. We favor genuine low-deposit accounts — the typical first deposit here is a few thousand pesos.
- Support. 24/7 or 24/5 live chat, coverage in Philippine time zones, and staff who know what GCash is.
We excluded AvaTrade, FP Markets, and Tickmill: all three accept Philippine residents, but none demonstrated the local funding rails this scorecard weights most heavily.
Best forex brokers in the Philippines 2026 — comparison table
| Broker | Regulation (your entity as a PH resident) | Min deposit | EUR/USD typical spread | Key funding methods | Standout feature |
|---|---|---|---|---|---|
| Exness | FCA, CySEC, FSA Seychelles, FSC BVI, FSCA; PH under the offshore entity | $10 (~PHP 500) | From 0.3 pips (Standard); from 0.0 (Raw/Zero) | GCash, Maya, local banks, cards, crypto | Fastest PHP funding + withdrawals |
| IC Markets | ASIC, CySEC, FSA Seychelles; PH under IC Markets Global (Seychelles) | $200 | From 0.0 pips + $3.50/side commission (Raw) | Cards, PayPal, Skrill, Neteller, bank wire | Lowest all-in trading costs |
| XM | CySEC, ASIC, DFSA, FSCA; PH under XM Global (FSC Belize) | $5 | From 0.8 pips (Ultra Low) | Cards, bank transfer, Skrill/Neteller | 100% deposit bonus + tiny minimum |
| Pepperstone | ASIC, FCA, CySEC, DFSA, SCB Bahamas; PH under the Bahamas entity | No minimum | From 0.0 pips + commission (Razor) | Cards, PayPal, Skrill, Neteller, bank transfer | Strongest regulation stack, full TradingView |
| Octa | CySEC, MISA, FSCA, FSC | $25 | From 0.6 pips | Cards, e-wallets, local bank, crypto | 50% deposit bonus on every deposit |
| FBS | FSC Belize (IFSC), CySEC, ASIC; PH under the Belize entity | $1 | From 0.7 pips (Standard) | GCash, local bank, cards, e-wallets | Cheapest entry point |
1. Exness — best overall for Filipino traders
Exness is the broker this scorecard was built around — the only one here that treats the Philippines as a first-class market. GCash and Maya deposits are instant, local bank transfers connect to BDO, BPI, Metrobank, UnionBank, and Landbank, funding from about PHP 500, and withdrawals back to GCash typically land in minutes.
Trading conditions are competitive too: Standard floats from 0.3 pips with zero commission; Pro from 0.1; Raw Spread from 0.0 with up to $3.50 per side per lot; Zero holds 0.0 pips on majors for roughly 95% of the day — a favorite among gold (XAU/USD) traders. Ignore the “unlimited leverage” marketing; keep it at 1:100 or below. Caveat: your account sits under Exness’s offshore entity, not its FCA or CySEC arms.
Pros – GCash, Maya, and direct local bank deposits in PHP; withdrawals typically instant – Spreads from 0.3 pips (Standard) to 0.0 (Raw/Zero); strong for gold – PHP 500 minimum — the most accessible serious broker here
Cons – PH accounts held under the offshore entity, not the FCA/CySEC arms — no compensation scheme – “Unlimited leverage” is dangerous in inexperienced hands
Not for you if: you need a tier-1 license covering your actual account, or you want deep research and education — Exness is an execution machine, not a classroom.
2. IC Markets — best for lowest spreads
IC Markets is the broker cost-obsessed traders benchmark everything else against. Its Raw Spread account averaged 0.02 pips on EUR/USD across independent 2026 test sessions, with a $7 round-turn commission — the tightest all-in cost in retail forex. The no-commission Standard account floats from around 0.8 pips. Our IC Markets review breaks down the account types.
Regulation is solid: ASIC, CySEC, and the FSA Seychelles entity (IC Markets Global) that onboards Philippine residents — though there’s no FCA license.
The part that costs it first place: funding. The PH cashier offers cards, PayPal, Neteller, Skrill, bank wire, and UnionPay — no GCash, no Maya, no local bank transfer, no PHP base currency. Every peso passes through a conversion, and the $200 minimum is the highest on this list.
Pros – Lowest measured EUR/USD costs of any broker here; true ECN execution, deep liquidity – ASIC + CySEC group licenses; no deposit or withdrawal fees from the broker
Cons – No GCash, Maya, or local bank rails; no PHP base currency – $200 minimum deposit — 40x the entry cost of XM; no bonuses or promos
Not for you if: your deposit method is a GCash wallet, or you’re starting with a few thousand pesos.
3. XM — best for beginners and small accounts
XM has onboarded retail traders since 2009 and remains one of the friendliest front doors for Filipinos: $5 minimum, spreads from 0.8 pips on the Ultra Low account, and a 100% deposit bonus (up to $1,000) padding your margin on Standard and Micro accounts. For a ₱1,000–₱5,000 starter account, that bonus extends the learning curve.
PH funding covers cards, bank transfer, Skrill, Neteller, and local payment systems — and PHP is supported as a deposit currency. We could not confirm GCash in the cashier as of September 2026. On regulation: the group holds CySEC, ASIC, DFSA, and FSCA licenses, but Philippine residents open under XM Global Limited, regulated by the FSC in Belize.
Pros – $5 minimum and a genuine 100% deposit bonus — the best small-account package here – PHP as a deposit currency; local bank transfer available; strong education library
Cons – Spreads from 0.8 pips are mid-pack — active traders pay more per trade than at Exness or IC Markets – PH accounts sit under the Belize entity; GCash unconfirmed as of September 2026
Not for you if: you’re a high-volume trader where per-trade cost dominates — the wider spreads quietly eat more than any bonus gives back.
4. Pepperstone — best regulated, weakest for peso funding
Pepperstone is the broker we’d hand to a trader who asks “which one is the safest company?” Licenses include ASIC, FCA, CySEC, DFSA, BaFin, CMA, and SCB (Bahamas) — the deepest bench here. Philippine residents onboard under Pepperstone Markets Limited, the SCB Bahamas entity, with leverage up to 1:200 on forex. Razor spreads from 0.0 pips with commission, a no-commission Standard account, and full TradingView execution. Read our Pepperstone review for the full breakdown.
So why fourth? On a scorecard built for Filipino traders, Pepperstone’s funding is the weakest of the six: no PHP base currency, no GCash, no Maya, no Philippine local bank option. You’ll fund a USD account by card, PayPal, Skrill, Neteller, or wire — every peso-to-dollar movement goes through your provider’s conversion rate. No minimum deposit and no funding fees soften the blow, but conversions are unavoidable.
Pros – Strongest multi-jurisdiction regulation in this lineup; Razor spreads rival IC Markets – MT4/MT5/cTrader plus full TradingView execution; no minimum deposit
Cons – No GCash, Maya, local bank rails, or PHP base currency — USD funding only – Conversion costs fall entirely on you – No deposit bonuses or promos
Not for you if: you fund from GCash or a Philippine bank and move money regularly — the conversion friction will annoy you within a month. Pick Exness instead.
5. Octa — best for bonus value and high leverage
Octa (since 2011) is the promo heavyweight: 50% deposit bonus on every deposit, leverage up to 1:1000, $25 minimum. Over repeat deposits, the recurring 50% beats XM’s 100%-up-to-$1,000 cap. The key detail: the bonus isn’t a one-time welcome offer — it applies to every deposit, so consistent funders keep getting the margin cushion. Check the bonus terms before relying on it, since bonus credit typically can’t be withdrawn directly.
Conditions are respectable: spreads from 0.6 pips with no commission, MT4/MT5 plus Octa’s own OctaTrader app, 24/7 live chat. Funding covers cards, Skrill, Neteller, crypto, and region-varying local bank transfer — but base currencies are USD and EUR only, and we could not confirm a GCash rail for PH residents as of September 2026. Regulation is mid-tier: CySEC, South Africa’s FSCA, and offshore licenses including MISA.
Pros – 50% deposit bonus on every deposit; 1:1000 leverage; $25 minimum – Crypto deposits and withdrawals; no deposit or withdrawal fees
Cons – No PHP base currency; GCash unconfirmed as of September 2026 – Mid-tier regulation — no ASIC or FCA entity
Not for you if: you trade large size where spread costs dominate, or you want the strongest regulatory wrapper.
6. FBS — cheapest entry, weakest regulation (read before depositing)
FBS lets you open a live account with $1 — roughly ₱56. No other broker here comes close, and for testing live markets with lunch money, FBS is the only name on this list that allows it. GCash deposits work alongside local bank transfers, cards, and e-wallets; spreads start from around 0.7 pips with leverage up to 1:3000. Our FBS review has the full account lineup.
Now read this twice: Philippine residents open under FBS’s Belize entity, regulated by the FSC of Belize. The group’s CySEC and ASIC licenses don’t cover your account — Belize-only coverage is the thinnest regulatory wrapper here, with no investor compensation scheme. FBS has operated since 2009, but that doesn’t change the legal structure.
Our honest take: FBS is fine for a $1–$50 test account to learn live-market mechanics with GCash funding — not for a serious balance. Graduate to Exness or IC Markets once the account is real money.
Pros – $1 minimum deposit — the lowest barrier to live trading anywhere – GCash and local bank funding confirmed for PH – Leverage up to 1:3000, MT4/MT5, 24/7 support
Cons – PH accounts under FSC Belize — weakest regulation here, no compensation scheme – Spreads from 0.7 pips are the widest in this lineup – Narrower product range than Exness or IC Markets
Not for you if: you’re depositing serious money. Use FBS to learn, not to build.
How to choose a forex broker in the Philippines
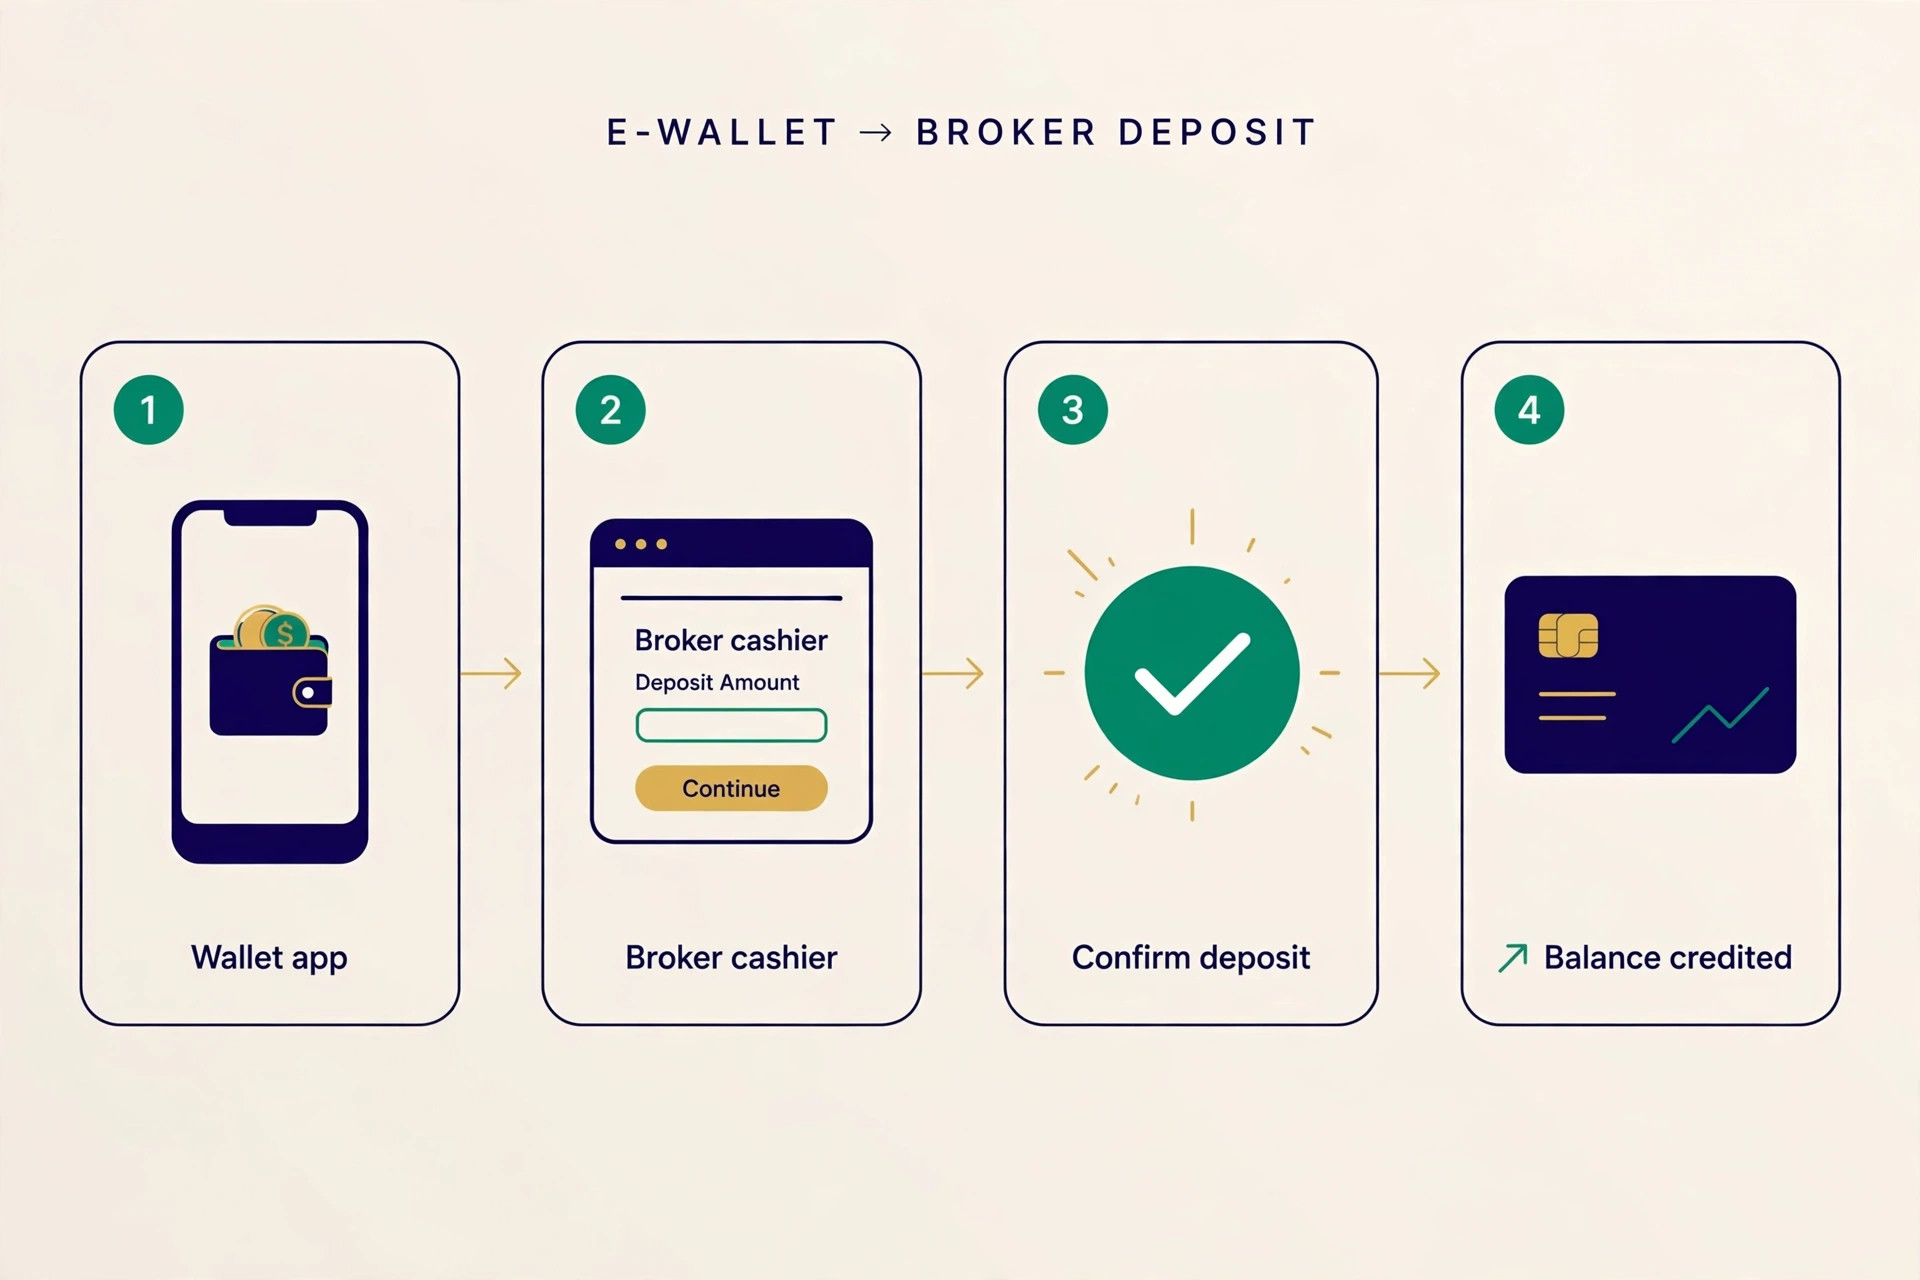
Start with the funding rails, not the spreads. A 0.1-pip spread advantage is worth about $1 per standard lot — one bad card conversion rate costs more than a month of that advantage. If you fund from GCash or a Philippine bank, shortlist Exness, FBS, XM, and Octa first. If you fund by card in USD and rarely move money, IC Markets’ and Pepperstone’s superior pricing is worth the conversion.
Check which entity holds your account. No broker here is licensed by the Philippine SEC. What matters is the offshore entity in your client agreement: Seychelles (IC Markets, Exness), Belize (XM, FBS), Bahamas (Pepperstone), or a mix (Octa). Tier-1 group licenses speak to company standards, but your legal protections come from the entity named in your contract.
Match the account to your size. Under ₱10,000 to start? XM’s $5 minimum and bonus, or FBS’s $1 entry, make sense. Funding ₱50,000+ and trading regularly? Exness Raw/Zero or IC Markets Raw will save real money on every trade. Don’t pay ECN-style commissions on a ₱2,000 account.
Mind swap-free if it applies. XM and FBS offer Islamic (swap-free) accounts; confirm exact terms with support, since conditions vary by instrument.
Frequently asked questions
Is forex trading legal in the Philippines?
Trading your own money through an offshore broker is not prohibited for individuals — but understand the landscape. The SEC licenses no local retail forex or CFD broker, and it has stated it does not allow registration of forex products in the nature of commodity or financial futures, CFDs, or similar derivatives, or their merchants/brokers, while public trading of these products remains suspended. The BSP supervises banks and national FX transactions — it does not license retail forex brokers. PAGCOR regulates gambling, not forex. Bottom line: no broker is “SEC-approved” for this, and anyone soliciting you locally for forex investment without registration is a red flag.
How do I fund a forex broker with GCash?
Of the brokers in this guide, Exness and FBS confirmed GCash in the cashier for Philippine residents. Log in, go to Deposit, select GCash, enter your mobile number and amount, then authorize in the GCash app or the secure portal — deposits are typically instant, and always from a GCash account in your own name. Without GCash listed (IC Markets, Pepperstone), use a Visa/Mastercard debit card, Skrill/Neteller, or bank transfer instead.
What is the minimum deposit to start forex trading in the Philippines?
From $1 (~₱56) at FBS to $200 at IC Markets. Realistic starting points: FBS ($1), XM ($5), Exness (~$10 / PHP 500), Octa ($25), Pepperstone (no minimum), IC Markets ($200). We suggest at least ₱2,000–₱5,000 so a few losing trades don’t wipe you out — a $5 account is for learning mechanics, not making money.
Can I open a trading account denominated in Philippine pesos?
Exness supports PHP deposits from PHP 500, and XM supports PHP as a deposit currency. IC Markets, Pepperstone, and Octa offer no PHP base currency — your account will be in USD or EUR with conversions each funding cycle.
Do I pay tax on forex trading profits in the Philippines?
Yes. The BIR treats trading gains as taxable income and you’re responsible for reporting them — your offshore broker won’t do it for you. Keep a spreadsheet of deposits, withdrawals, and net annual profit.
Final verdict
For most Filipino traders in 2026, Exness is the right answer: the only broker here pairing competitive costs with GCash, Maya, and local bank funding in pesos, instant withdrawals, and a PHP 500 minimum.
Otherwise: IC Markets for the lowest costs (USD card funding); XM for starting under ₱5,000 with the bonus; Pepperstone for regulatory depth; Octa for recurring bonuses and 1:1000 leverage; FBS for going live with pocket change.
Whatever you pick: verify fully before depositing, test a withdrawal early, keep leverage modest, and never trade money you need for rent. The broker is infrastructure — your risk management decides the outcome. See our forex broker reviews hub, our guide to forex trading in Singapore, and our guide to forex brokers that accept crypto deposits — or start from the homepage.
Risk disclaimer: Forex and CFD trading involves a high level of risk and may not be suitable for all investors. Leverage magnifies both profits and losses. The majority of retail investor accounts lose money trading CFDs. Consider whether you understand CFDs and can afford the high risk of losing your money. Past performance is not a reliable indicator of future results. This article is for informational purposes only and does not constitute investment advice.
Affiliate disclosure: This article contains affiliate links. If you open an account through one of our links, forexcryptohub.com may earn a commission at no additional cost to you. Rankings reflect our own evaluation criteria — Pepperstone’s weak PH funding rails cost it a higher slot here, which a commission-chasing list wouldn’t say.